Short answer: A sole proprietorship is the practical start for one person, a light setup and modest profit. A limited company comes forward when a partner will join, when a flat corporate rate is worth weighing as profit grows, or when a corporate customer wants a limited title. The right form depends on expected profit, liability and how cash will be taken out.
The first question in an Ankara formation meeting is which one is cheaper. Cost is not only the fee on formation day. Annual tax, how profit reaches the owner and who is liable for debts are the same decision. The sole-proprietor steps are in how to set up a sole proprietorship. Limited-company documents are in company formation documents.
Tax: a rising scale and a flat rate
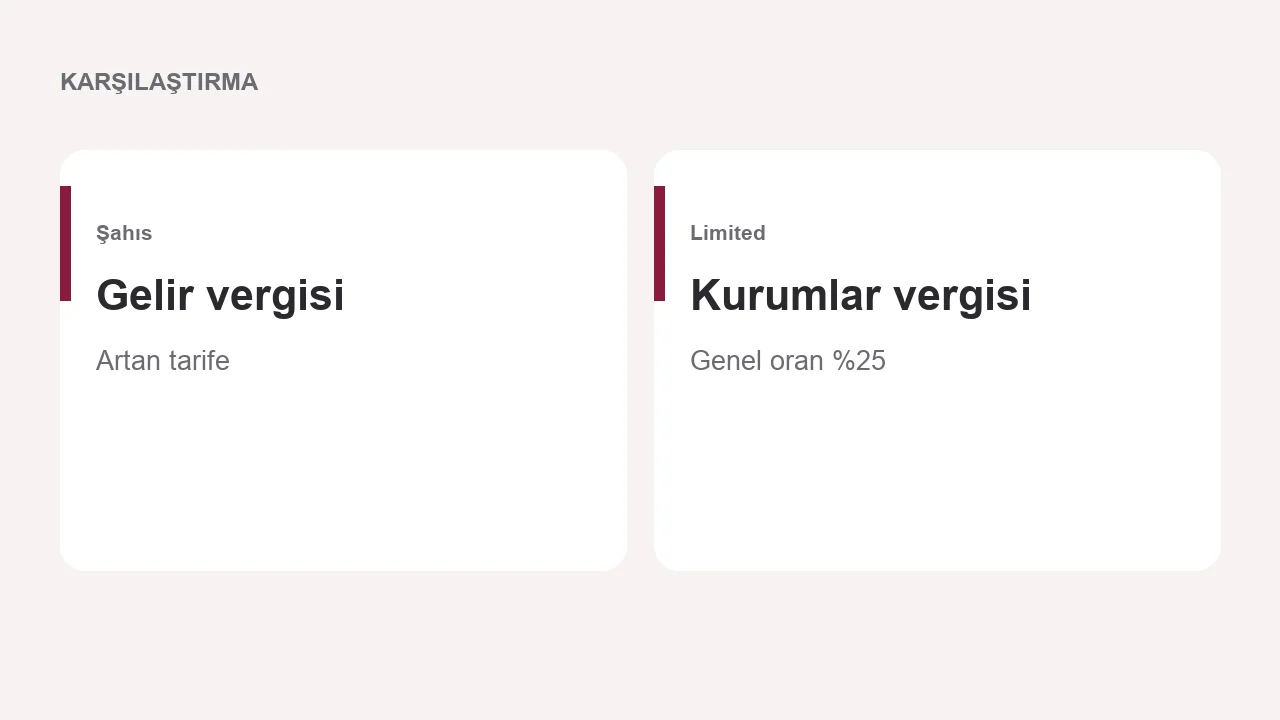
A sole proprietorship's commercial profit enters the income-tax scale. The scale rises with profit. A limited company pays corporate tax. On the Revenue Administration's 2026 table the general corporate rate is 25 percent. Reduced rates can apply to export income and to manufacturing by a business with an industrial registry certificate. Banks and the financial institutions on that table are at 30 percent. Those reductions do not replace the personal scale.
When a limited company distributes profit, withholding applies. Profit left in the company is not distributed. In a sole proprietorship the profit is the owner's income whether or not it is withdrawn. "Corporate tax is lower" is incomplete until you say how the cash will be used.
| Topic | Sole proprietorship | Limited company |
|---|---|---|
| Tax | Rising income-tax scale | General corporate tax at 25 percent |
| Taking cash out | The profit is the owner's | Withholding on a distribution |
| Liability | Personal assets for trade debts | In principle the committed capital; special rules for public debts |
| Formation | Tax office; trade registry if required | MERSİS, articles, trade registry, tax office |
| Partners | One owner | One or more shareholders |
Four checks before you choose
First, what profit is expected next year. At a low level the bottom of the personal scale can be lighter than 25 percent. As profit climbs, the scale rises and the flat corporate rate, with profit left in the company, is recalculated. Second, how cash will be taken out. In a limited company personal spending from the till is a distribution or a wage. A distribution has withholding. A wage brings payroll and social security. Third, partners. A second person putting in capital cannot sit inside a sole proprietorship. Fourth, the customer. Some buyers and some tenders want a limited title and a balance sheet.
A single-shareholder limited company is still a company. The tax is corporate tax, and formation goes through the trade registry. Moving from a sole proprietorship to a limited company is a new entity and a transfer, not a change of sign. Open invoices, the lease and a marketplace shop stay on the old tax number until they are moved. The cut-off date has to be the same on the contract and on the marketplace panel.
A consultant or a developer selling to a customer abroad asks the same four questions. A service-export exemption does not open because you formed a limited company. A sole proprietorship can use it when the conditions are met. The conditions are in service export tax exemption. Formation itself, for either form, is on our company formation page. Online sellers often start as a sole proprietorship and reconsider a limited company as turnover grows. See starting an e-commerce company.
Frequently asked questions
Can one person form a limited company?
Yes. One shareholder is not a sole proprietorship. The tax is still corporate tax, and formation goes through the trade registry.
Does a sole proprietor pick their tax bracket?
No. Profit falls into the bracket it reaches. Brackets are updated each year.
Does a limited company always pay less tax?
No. The general corporate rate is 25 percent. A modest profit can sit in a lower personal bracket. Withholding on a distribution is part of the sum.
Is the owner's home exposed in a sole proprietorship?
For trade debts the owner is liable with personal assets. In a limited company the rule is the committed capital, with special rules for public debts.
Can the form be changed later?
Moving from a sole proprietorship to a limited company is a new formation and a transfer. The title does not convert by itself.
Which one opens faster in Ankara?
The sole proprietorship is the shorter file. A limited company needs articles and trade-registry registration. Missing papers slow both.
Conclusion
A sole proprietorship opens quickly, with a rising income-tax scale and personal liability. A limited company runs on a general corporate rate of 25 percent, withholding when profit is distributed, and trade-registry registration. Partners, expected profit and who bears the debt decide the form. The fee on formation day does not.
Ankara Muhasebeci opens both from our Kızılay office, with the profit and liability figures in the same conversation. See company formation or write to us.