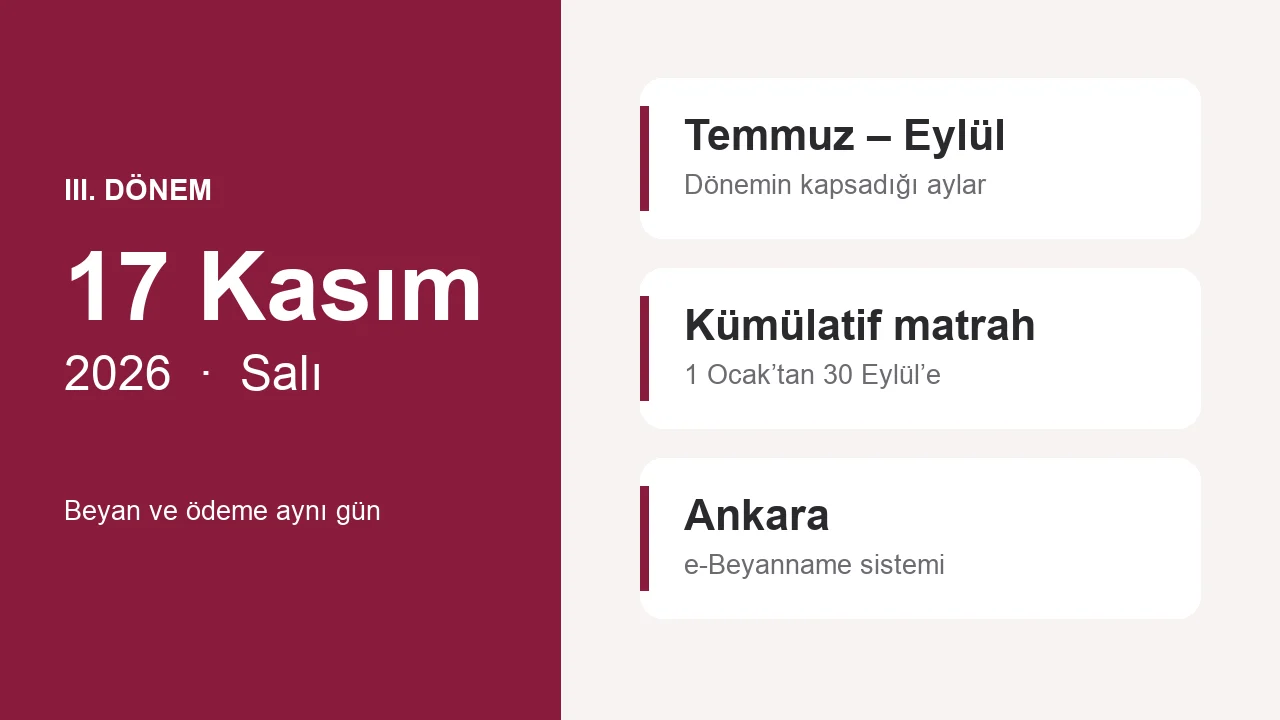
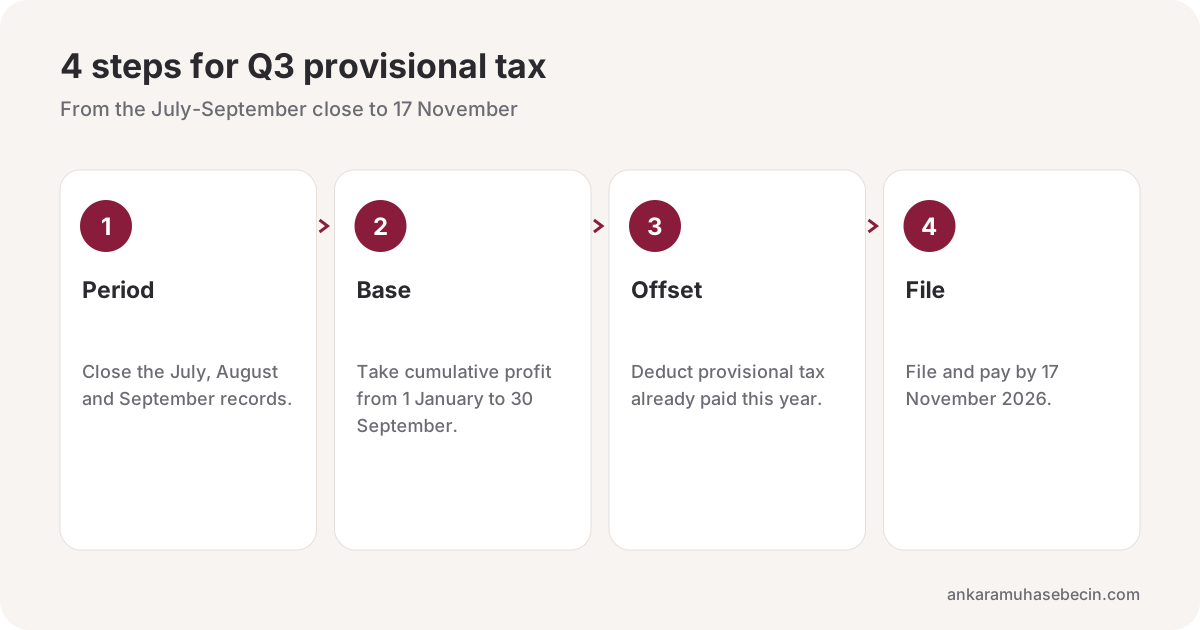
Short answer: Turkey's third provisional tax period for 2026 covers profit from 1 July to 30 September. On the Revenue Administration's 2026 tax calendar, the return and the payment are both due on 17 November 2026. The tax is calculated on cumulative profit from the start of the year through 30 September, and provisional tax already paid in 2026 is offset. Taxpayers in Ankara file this period on the existing e-Beyanname system, not on the new e-Beyan pilot.
The work belongs in October, not on the evening of the deadline. September invoices, expense documents and the prior-period offset have to be closed before the base is reliable. This note sets out the order we use at Ankara Muhasebeci, where the rates come from, and why Ankara does not share the pilot screen.
Where the 2026 calendar puts each period
Provisional tax is an advance payment credited against the annual income or corporate tax. The Revenue Administration's 2026 calendar lists three periods for the year. The first (January-February-March) was due on 18 May 2026. The second (April-May-June) was due on 17 August 2026. The next one is the third: July-August-September, due on 17 November 2026. Payment is made within the same deadline as the return.
There is a fourth period as well. The same calendar placed the October-November-December 2025 period on 17 February 2026. The fourth period of 2026 is October, November and December. Its filing day falls in 2027, outside the 2026 calendar, and should be confirmed when that calendar is published. Treating the third period as the last provisional return of the year is no longer correct.
| Period | Months | Day on the 2026 GİB calendar |
|---|---|---|
| 2025 / IV | October-November-December 2025 | 17 February 2026 |
| 2026 / I | January-February-March | 18 May 2026 |
| 2026 / II | April-May-June | 17 August 2026 |
| 2026 / III | July-August-September | 17 November 2026 |
17 November 2026 falls on a Tuesday, so the calendar does not move this item. An extension applies only if the Revenue Administration announces one. Waiting for that announcement until the evening of 17 November also means filing into a busy system.
The base is not just the last three months
The third-period return is not a separate tax on July, August and September alone. The base is cumulative profit from the opening of the accounting period through 30 September. For a limited or joint stock company that is nine months of corporate profit. The same logic applies to an income-tax taxpayer with commercial or professional income: the result from 1 January through the end of September is what matters. Taxpayers on the simplified regime (basit usul) are outside this return.
Provisional tax paid for the first and second periods of the same year is deducted from the tax calculated on that cumulative base. The amount due in the third period is the remainder. If the period closes at a loss and the cumulative tax falls below what was already paid, nothing further is payable in November. The excess is not refunded in cash that month; it is credited on the annual return.
On the Revenue Administration's provisional-tax rate table for 2026, the rate is 15 percent for income-tax taxpayers and 25 percent as the general rate for corporate taxpayers. Banks, financial institutions, insurers and the other entities listed on that table are at 30 percent. Where a reduced corporate rate applies, such as export income or manufacturing by a business that holds an industrial registry certificate, provisional tax follows that reduced rate. One rate is not applied to the whole profit in a single line; the split is made before the return is filed.
| Taxpayer | 2026 provisional rate | What is offset |
|---|---|---|
| Commercial and professional income | 15 percent | Provisional tax paid in the same year |
| Companies, general rate | 25 percent | Provisional tax paid in the same year |
| Financial institutions on the table | 30 percent | Provisional tax paid in the same year |
| Income at a reduced corporate rate | The reduced rate for that income | Provisional tax paid in the same year |
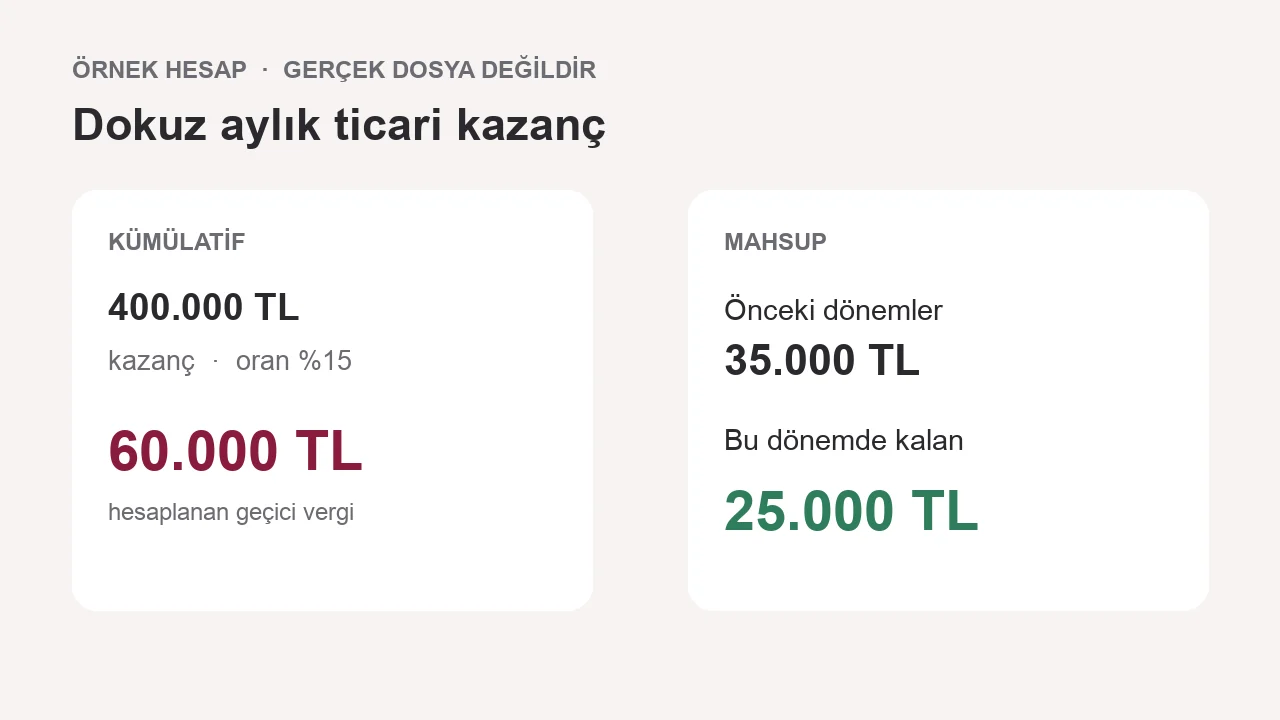
The figures below are not taken from a client file; they only show the offset. On commercial profit of 400,000 TL for nine months at 15 percent, the calculated tax is 60,000 TL. If 35,000 TL was paid in the first two periods, 25,000 TL remains for the third. On corporate profit of 1,000,000 TL at the general 25 percent, the calculated tax is 250,000 TL. If 140,000 TL was paid earlier, 110,000 TL remains. An exemption, a reduced rate or a withholding credit changes this round example.
Ankara is not in the e-Beyan pilot
From 1 October 2026, income and corporate provisional returns in the provinces named by the Revenue Administration are accepted on the new e-Beyan system. Those provinces are Afyonkarahisar, Eskişehir, Kayseri, Kırıkkale and Kırşehir. The announcement does not change the calculation or the 17 November deadline. It changes the screen used for the July-September return in those five provinces. Earlier periods stay on the old e-Beyanname system even there.
Ankara is not on that list. A taxpayer registered with an Ankara tax office files the third provisional period of 2026 through the existing e-Beyanname (BDP) system. A business that also has a registration in a pilot province uses e-Beyan for that registration. Using the wrong screen can leave the return unfiled. Missing the channel is as much a delay as missing the date.
Corporate taxpayers also attach the beneficial-owner notification to the provisional return. The Revenue Administration calendar lists that form next to the third period. Leaving it for the annual return leaves the corporate filing incomplete. The advisor who prepares the return and the person who keeps the share register should be looking at the same file.
What to close before 17 November
Filing day is a poor day to start entering records. For an Ankara file we close the period in this order:
- Income: e-Invoices and e-Archive invoices issued through the end of September have to be in the period's sales. Mixing the two document types mixes the base. See e-Invoice vs e-Archive.
- Expenses: Purchase invoices, rent, payroll and finance costs go in with their documents. An amount without a document is not deducted at will.
- Earlier returns: Provisional tax assessed and paid for the first and second periods is the offset. An unpaid assessment is not deducted as if it had been paid.
- Companies: The beneficial-owner form is attached in its current form if the ownership has changed.
- e-Ledger: For monthly upload, the July berat is due by 10 November 2026 for income-tax taxpayers and by 16 November 2026 for other taxpayers. That upload does not replace the provisional return.
If a marketplace seller's commission, returns and payout for September are still open, nine-month profit looks higher than it is. The same happens when a courier or a freelancer tries to complete expenses with receipts that arrive after September: the return gets corrected twice. Monthly bookkeeping is this list. Period close is part of our bookkeeping and accounting work.
Mistakes we keep seeing
Third-period errors usually land in the same place: the base is incomplete, or the offset comes from the wrong payment.
- Taxing only July-September profit and leaving January-June out
- Offsetting provisional tax that was assessed but not paid
- Looking for an Ankara file on the pilot provinces' e-Beyan screen
- Applying 25 percent to income that has a reduced rate, or the reduced rate to ordinary profit
- Omitting the beneficial-owner form from a corporate return
- Moving a September invoice into October, or an October expense back into September
If, once annual profit is known, the provisional base is found to have been short by more than 10 percent, the shortfall can lead to an assessment and a penalty. The third period is not a rough interim return. Nine-month records are also an early view of the year-end tax. Uncertain lines on rates, exemptions and offsets are reviewed before filing as part of tax advisory.
Frequently asked questions
When is the third provisional tax paid?
On the Revenue Administration's 2026 calendar, the July-August-September period is filed and paid by 17 November 2026. There is no separate payment date.
Does Ankara file on e-Beyan?
No. The 1 October 2026 pilot covers Afyonkarahisar, Eskişehir, Kayseri, Kırıkkale and Kırşehir. An Ankara taxpayer files the third period on the existing e-Beyanname system.
Which months are added up?
Not only July, August and September. Cumulative profit from 1 January through 30 September is used. Provisional tax already paid in 2026 is deducted from that tax.
Is there a fourth period in 2026?
Yes. October-November-December is the fourth period. The 2025 fourth period was filed on 17 February 2026. The day for the 2026 fourth period is confirmed on the 2027 calendar.
Is a return filed if nothing is payable?
Yes. If the cumulative result is below the tax already paid, nothing further may be collected this period. The excess is credited on the annual return. It is not refunded automatically in November.
Does the simplified regime file provisional tax?
Taxpayers on the simplified regime are outside this return. Commercial income, professional income and corporate taxpayers are within it.
Conclusion
The third provisional tax period of 2026 is filed and paid by the evening of 17 November 2026. The base is nine months, and a taxpayer in Ankara files on e-Beyanname rather than the e-Beyan pilot. The rate is 15 percent for income-tax taxpayers and 25 percent for companies at the general rate, and reduced-rate income keeps its own rate. Without the prior payments offset and the September documents closed, the date is only a line on the calendar.
Ankara Muhasebeci closes the period before filing week for companies, online sellers and freelancers, from our Kızılay office and for clients in Çankaya and the other districts. To close the third period together, see tax advisory or write to us.